
If you hear “cargo insurance” and immediately picture 18-wheelers and freight brokers, you’re not alone. It’s easy to assume this is a trucking-industry-only product. But the truth is, a surprising number of non-trucking businesses are hauling goods every day without realizing they have a coverage gap — and it’s usually not until something goes wrong that they find out.
Short answer: You might need cargo insurance even if you never touch a semi-truck. Here’s how to know.
What Cargo Insurance Actually Covers
Cargo insurance (sometimes called Motor Truck Cargo insurance) protects the goods being transported — not the vehicle, and not the driver. If a shipment is damaged, stolen, or destroyed while in transit, cargo coverage pays to replace or repair it.
This is different from:
- Commercial auto insurance, which covers the vehicle and liability for injuries/property damage in an accident
- General liability insurance, which covers third-party bodily injury or property damage unrelated to the cargo itself
- Property insurance, which typically only covers goods while they’re sitting in a warehouse or storefront — not while they’re moving
That gap between “property coverage stops” and “cargo coverage starts” is exactly where a lot of businesses get caught.
Who Actually Needs This (Even Without a Trucking Operation)
You may need cargo coverage if your business does any of the following:
You transport your own product to customers or job sites. Landscapers hauling mulch and equipment, caterers delivering food and rental equipment, furniture stores doing their own deliveries, contractors moving materials to a site — if company-owned goods are damaged in an accident or stolen from a vehicle, cargo insurance is what pays for that loss, not your auto policy.
You transport other people’s property. Movers, dry cleaners with pickup/delivery, appliance repair techs hauling customer units back to the shop, art or antique dealers — anytime you’re legally responsible for someone else’s property while it’s in your vehicle, you have “bailee” exposure. Cargo insurance (or a bailee’s customer coverage form) fills that gap.
You occasionally haul freight for others, even informally. Some businesses pick up side income hauling for a local shipper without being a licensed “motor carrier.” If you’re compensated for hauling someone else’s goods, you may trigger requirements similar to a for-hire carrier — and your personal or standard commercial auto policy likely excludes this entirely.
You run a retail, wholesale, or distribution business with your own fleet. Even a single box truck moving inventory between a warehouse and a storefront is exposed. One bad pothole, one theft from a parking lot overnight, one rear-end collision — and that inventory is gone unless cargo coverage is in place.
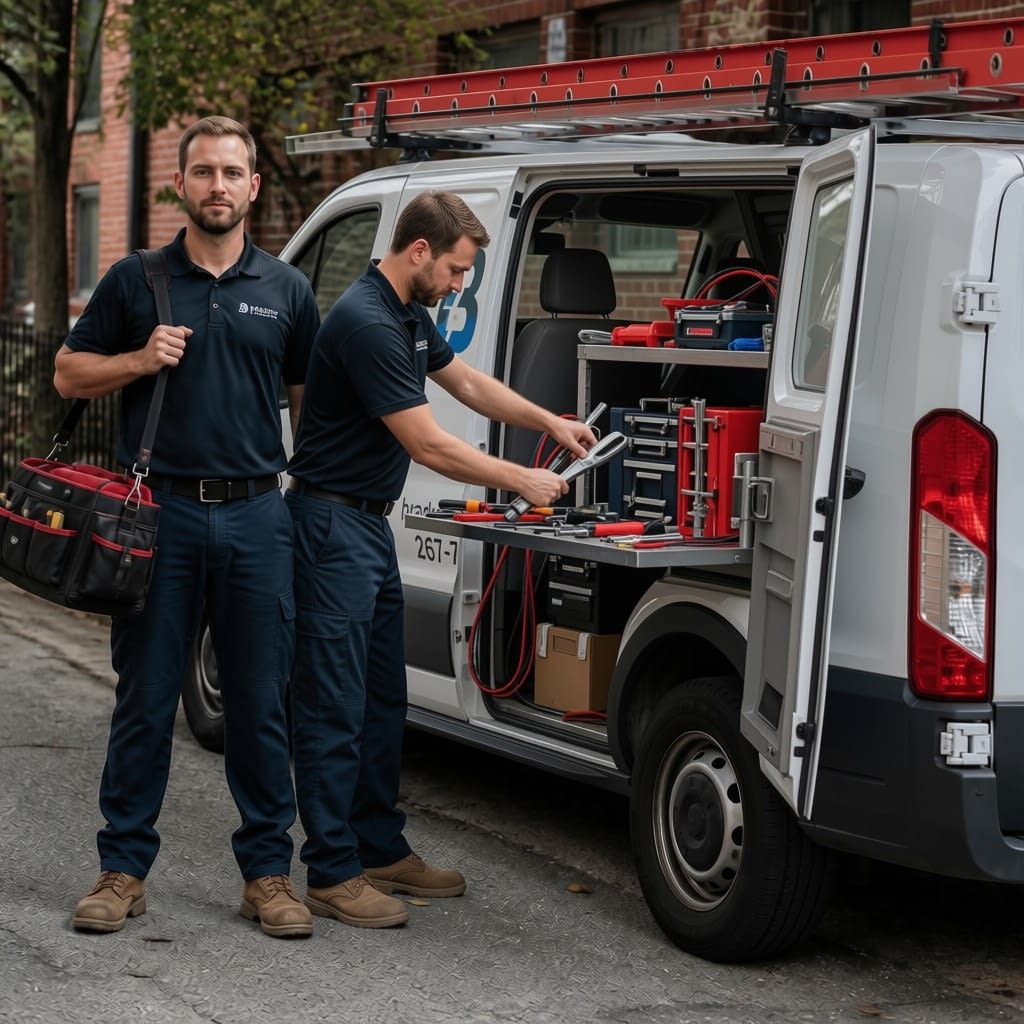
You’re a contractor or tradesperson with expensive tools and materials in transit. Tools and materials in a work van are often underinsured. A basic auto policy generally won’t reimburse you for a truck bed full of stolen equipment.
If You’re a Courier or Local Delivery Driver, This Isn’t Optional in Practice
If you contract with retailers, medical labs, auto parts suppliers, or regional distribution companies as a courier or last-mile delivery service, you’ve probably already seen this firsthand: most of these contracts come with an insurance requirements page before you ever load a package.
It’s common for that page to require anywhere from $50,000 to $150,000 in cargo coverage, depending on the value of what you’re hauling and who you’re contracting with. But here’s the part that catches people off guard — cargo is rarely the only line item. That same contract will usually also demand specific limits for auto liability, general liability, and sometimes even property or workers’ comp, all bundled together with their own minimums and endorsement requirements.
This is exactly the kind of situation where working with an agent who specializes in commercial auto and cargo — rather than piecing coverage together on your own — pays for itself. Reading a client’s insurance requirements sheet and translating it into the right combination of policies and limits isn’t intuitive, and getting even one piece wrong can mean losing a contract or getting flagged during a compliance audit. An agent who does this regularly knows what a distribution company or medical courier client is actually going to ask for before you even show them the paperwork.
What About the Legal Requirement Question?
This is where a lot of confusion comes from. The federal cargo insurance minimums under the FMCSA (Federal Motor Carrier Safety Administration) apply specifically to for-hire motor carriers — companies licensed to transport other people’s freight for compensation across state lines. If that’s not your business model, those specific federal minimums don’t apply to you.
But “not legally required” and “no exposure” are two very different things. Plenty of businesses that aren’t regulated motor carriers still carry thousands (or hundreds of thousands) of dollars of product, equipment, or client property in a vehicle on any given day. The absence of a federal mandate doesn’t mean the risk isn’t real — it just means nobody is forcing you to cover it. That decision is left up to you.
A Real Example: The $150,000 Gap Nobody Caught
Here’s a case that makes this whole conversation less theoretical. With the client’s permission, we’re sharing what happened — though we’re keeping their name out of it.
We recently worked with a dermatology group that runs a small fleet of vans to treat patients directly at nursing homes — skin cancer screenings, biopsies, and other in-facility treatments for residents who can’t easily travel to a clinic. Each van is essentially a mobile treatment room, outfitted with specialized medical equipment worth well over $150,000 per vehicle.
When they came to us, their existing insurance program looked reasonable on the surface: commercial auto was in place, and general liability was in place. But nobody had ever specifically covered the equipment inside the vans. There was no cargo or inland marine coverage on any of it.
In practice, that meant if a van was broken into overnight, involved in an accident, or caught fire, six figures’ worth of diagnostic and treatment equipment had no path to being replaced. The vans were insured. The liability exposure was insured. The actual tools this practice depends on to see patients and generate revenue were not insured at all.
This is a textbook example of why “we’re not a trucking company” isn’t the right question to ask. The right question is: what’s inside the vehicle, and who pays if it’s gone tomorrow? A dermatology group never thinks of itself as having a “cargo” exposure — but rolling clinics, mobile labs, mobile veterinary units, and similar operations are exactly the kind of business where this gap shows up again and again, often for the first time when an agent actually asks to see the equipment list.
If You Run a Fleet of Electricians, Plumbers, or Painters
The dermatology example above happens to involve medical equipment, but the same gap shows up constantly with electricians, plumbers, painters, HVAC techs, and similar trades — especially once you’ve grown past one or two trucks.
A quick clarification on terminology, since it trips a lot of business owners up: inland marine insurance is the broader category, and cargo coverage typically falls under it. “Inland marine” covers property in transit or property that moves between locations (tools, equipment, materials), while “cargo” or “motor truck cargo” is often the specific form used for goods being hauled in a vehicle. In practice, your agent may write this as an inland marine policy, a cargo policy, or a contractor’s equipment floater — the important thing isn’t the exact label, it’s making sure the coverage actually exists.
If you own a small to medium-size fleet and your drivers are carrying several thousand dollars of tools, materials, or equipment in each van or truck, and you don’t have an inland marine or cargo policy in place, you likely have a costly gap — and it’s one of the easier ones to fix once it’s identified.
As your business grows, this is exactly where having an agent who functions like part of your team, rather than just a policy vendor, starts to matter. A good agent takes the time to understand what your business actually does, how it’s growing, and what’s riding around in your vehicles — then customizes coverage around that, instead of selling you a generic package. Calling a large call-center carrier can work fine for a simple auto policy, but those reps typically aren’t equipped to ask the follow-up questions that catch a gap like “what’s actually inside the van.” That’s the kind of thing that only gets caught by someone who knows your business specifically.
A Quick Way to Check Your Exposure
Ask yourself three questions:
- Does my business ever put product, equipment, or someone else’s property inside a vehicle and drive it somewhere?
- If that vehicle were broken into, stolen, or in an accident tomorrow, would my current policies actually pay to replace what was inside?
- Have I ever assumed “my commercial auto policy covers that” without actually confirming it in writing?
If you paused on question 2 or 3, it’s worth a conversation with your agent before it’s tested by an actual claim.
The Bottom Line
You don’t have to own a trucking company to need cargo insurance — you just have to be moving something valuable from Point A to Point B and be financially responsible for it if things go sideways. For a lot of small and mid-sized businesses, this is one of the most overlooked gaps in their insurance program, simply because “cargo insurance” sounds like someone else’s problem.
If you’re not sure whether your current policies actually cover goods in transit, that’s exactly the kind of thing worth a quick policy review — not a guess.
